Holding each other up
On 30 September 2008 the Irish government guaranteed six of its banks. By the next morning, the price of insuring against those banks’ default had fallen from roughly 400 basis points to 150. The price of insuring against Ireland’s own default went the other way: it quadrupled to over 100 basis points within a month and reached 400 within six. The risk of the Irish financial sector had been substantially transferred to the government’s balance sheet.
Nothing was removed. The banks’ risk moved to the state, and the state’s balance sheet was, to a considerable extent, held by the banks. The two exposures were not of the same kind: the state had taken on the banks’ possible losses as a liability, while the banks held the state’s debt as an asset. But each now depended more heavily on the other’s ability to pay.
Joined at the hip
What the Irish case showed in one country, the European data showed across many. Before the autumn 2008 bailouts, there was almost no relationship across European countries between a government’s debt ratio and the market price of its default risk. After them, the relationship was strong and positive. A debt ratio that markets had treated as background became something they priced.
The return path runs through bank balance sheets. Euro area banks hold large amounts of government debt, and a disproportionate share of it has been their own government’s. When the sovereign’s credit risk rises, those bonds lose value, which eats into the banks’ capital.
Separately, the implicit promise that the state will support its banks is worth less, because the promise is only as good as the state making it, and the banks’ own credit risk rises with it. After the bailouts, a 10% rise in a sovereign’s credit default swap spread went with roughly a 0.9% rise in its banks’ spreads; before them, there was no such feedback.
The banks held so much of it for several reasons at once. Regulation treats exposures to euro area governments in their own currency as carrying a zero risk weight, so holding them costs no risk-based capital.
Governments also appear to have leaned on their banks: during the crisis, domestic banks in fiscally stressed countries were considerably more likely than foreign banks to add to their holdings of home bonds in months when their government had large amounts of debt to roll over. Banks that had received government support, small banks and banks with weaker balance sheets were particularly susceptible.
Banks themselves name political pressure, their business models and the perception of home bonds as safe and highly liquid, and when domestic bonds look attractive the leverage ratio is the only regulatory barrier to holding a great many of them.
The cost of that arrangement shows up when the sovereign stumbles. Government defaults are followed by falls in private credit, and the falls are larger where banks hold more government debt. A sovereign in trouble is also, through its banks, a squeeze on lending to everyone else.
Someone else’s printing press
Why the spiral bit so hard in the euro area and not elsewhere shows in a comparison of Spain and the United Kingdom in 2011. The UK had a higher debt ratio, around 89% of GDP against Spain’s 72%, yet Spain paid about 200 basis points more to borrow. The difference was not simply the size of the debt; it was also the currency it was written in.
Members of a monetary union issue debt in a currency over which they have no control. A government borrowing in a currency its own central bank issues can always be supplied with the cash to pay bondholders at maturity. A euro area government cannot count on that, and markets know it.
That opens the door to self-fulfilling crises. Investors who fear a default demand higher yields; higher yields make the debt harder to carry; the liquidity crisis turns into a solvency crisis. The fear can produce its own justification. Paul De Grauwe’s remedy is a lender of last resort in the government bond market: a central bank willing to buy without limit, so that a run has nothing to win.
The ECB came to that role in stages. From May 2010 its Securities Markets Programme bought government bonds, sterilised week by week and without a volume announced in advance, but framed as a repair for malfunctioning markets rather than a commitment.
On 6 September 2012 it replaced the programme with Outright Monetary Transactions, for which “no ex ante quantitative limits are set”. The purchases were conditional on the country accepting an EFSF or ESM programme, with its conditions attached. OMT was never activated, in part, Willem Buiter argued, because fiscally fragile governments were reluctant to submit to its conditions.
The announcement appears to have been enough. A significant part of the surge in peripheral spreads in 2010 and 2011 had been disconnected from debt ratios and fiscal space and associated with self-fulfilling negative sentiment. Once the commitment was in view, Spain’s two-year yield fell from 6.9% in late July 2012 to below 3% by early September without a bond being bought, and the contagion running from Spain to other sovereigns dissipated after Draghi’s pledge of July 2012.
In July 2022 the ECB added the Transmission Protection Instrument, to counter “unwarranted, disorderly market dynamics” in a member state’s bond market. Its activation depends on a cumulative list of criteria, among them that the country is not under an excessive deficit procedure or, if it is, has not been found failing to act on it, and that its public debt is judged sustainable.
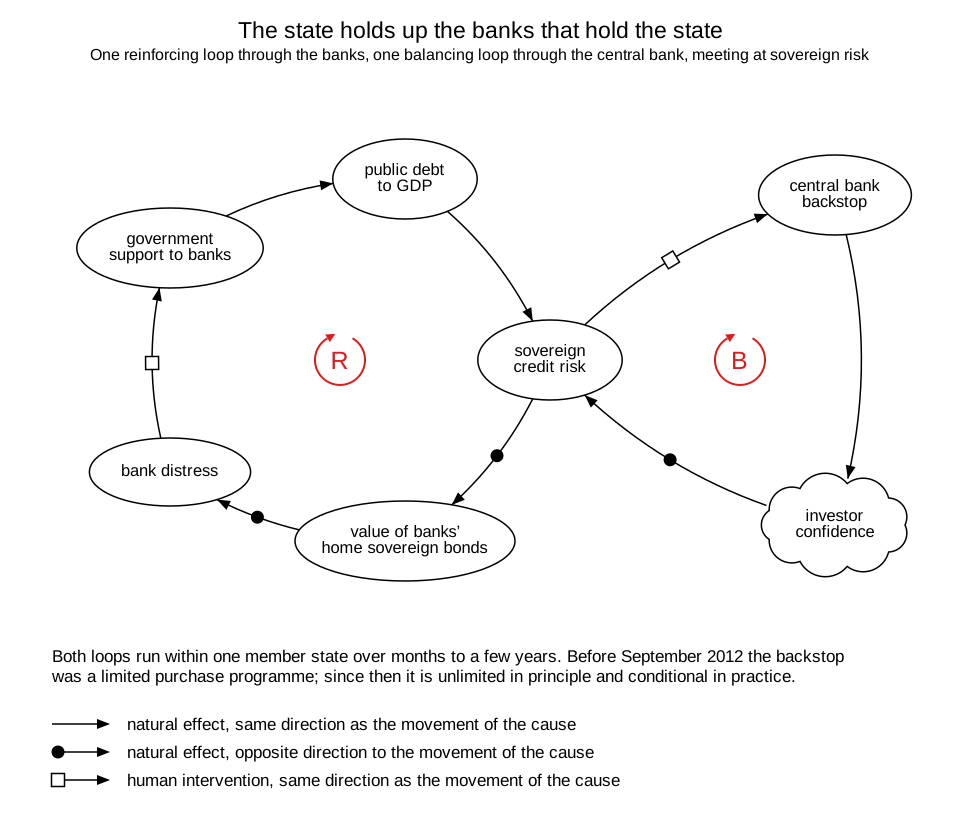
The spiral and the central bank’s promise meet at one price, the market’s price of a member state’s default. The spiral is slow: it works through bank balance sheets and a national budget over months to a few years, each worsening preparing the next. The promise is fast, because it works on expectations: an announcement brought spreads down in 2012 before a single bond was bought.
Each turns on a decision. A government chooses to support its banks, and a central bank chooses to stand behind a government’s bonds. Neither choice is automatic, and the second one comes with conditions.
Strings attached
The conditions are where the spiral and the promise stop being a match for each other. The spiral runs fastest in a country whose debt ratio is already high and rising. On a plain reading of the criteria, a country in that position is the one most likely to be found failing to act under an excessive deficit procedure, or to have its debt path judged unsustainable, and so the one least likely to qualify for the instrument meant to calm its bond market.
Under OMT the same country would first have to accept a programme. The worse a sovereign’s position becomes, the harder the conditions attached to its rescue are to meet. The promise holds in principle everywhere and in practice most reliably where it is least needed.
A backstop without conditions invites the moral hazard its critics have long identified, and the ECB’s mandate is price stability, not the solvency of any particular treasury. But it leaves the spiral with an exit that narrows as the spiral speeds up.
Still under construction
Parts of the spiral are weaker than in 2014. The domestic share of euro area banks’ sovereign bond holdings fell from 39% in 2014 to around 28% at the end of 2025. Banks’ sovereign holdings stand at about 170% of their core equity capital, against 190% in 2014, while remaining roughly 9% of total assets; risk-based capital ratios have nearly doubled since the financial crisis. More capital does not stop losses on government bonds from weakening a bank, but it widens the cushion the loss has to cross.
The rescue has moved less than the balance sheets. Bail-in now puts shareholders and creditors ahead of taxpayers, but deposit insurance is still national. The European Deposit Insurance Scheme, proposed in November 2015 as the third pillar of banking union, has not been adopted. National deposit guarantee schemes still contribute to the nexus. As long as depositors in a member state look to that member state for their guarantee, the decision to rescue remains a national one, financed on a national balance sheet.
The proposals aimed at cutting the spiral outright have stayed proposals. The spiral could be avoided by capping banks’ holdings of their own government’s debt against their equity. The equity needed would shrink further if banks held only the senior tranche of a diversified portfolio of euro area bonds, the so-called ESBies. Another route is pooling debt up to 60% of GDP in senior “blue” bonds. Neither has been built.
Paid in full
The spiral has a direction that its vocabulary of spreads and ratios hides. Run through a crisis, it moves losses away from those who lent to the banks and towards those who never did.
Ireland shows the route in its plainest form. The guarantee of September 2008 covered not only deposits but covered bonds, senior debt and dated subordinated debt; shareholders were left to lose, the senior creditors were made whole.
In November 2010 there would have been no rescue programme had the government imposed losses on senior bondholders. When it tried in March 2011, the withdrawal of emergency liquidity was used as an explicit threat to prevent it. The ECB’s position on both occasions contributed to the inappropriate placing of significant banking debts on the Irish citizen, and the refusal of burden sharing increased the overall cost of the crisis for the Irish people.
Senior creditors were paid, and the state took on the cost. The Comptroller and Auditor General puts it at around €42 billion net, about €7,600 for each of the 5.5 million people living in Ireland in 2026, still carried as debt that costs almost €650 million a year in interest.
When the state sold the last of its AIB shares in June 2025, the Department of Finance reported it above break-even on its €29.4 billion investment in AIB, Bank of Ireland and PTSB. Anglo Irish Bank and Irish Nationwide, merged in 2011 as IBRC, are outside that sum; their net cost to the state was €39.1 billion.
Greece shows the same transfer by a different route, and at a larger scale. Of about €216 billion lent in the first two programmes, less than 5% reached the Greek budget: the rest went to repaying and servicing existing debt, recapitalising Greek banks and paying private creditors to accept the 2012 restructuring.
Counting interest and bank recapitalisation as public spending, and adding the 2015 third programme and money from outside the programmes, puts about half towards public expenditure instead, which changes the label and not the direction. What the loans bought was the continuity of payments to creditors. What Greek households received was the adjustment attached as the condition.
Many of those creditors were banks elsewhere in the euro area: at the end of 2009 French and German banks had claims of $31 billion and $23 billion on the Greek state. The IMF’s own evaluation found that putting off the restructuring allowed many private creditors to escape, shifting the debt into official hands and leaving taxpayers and the official sector on the hook. The rescue funds still file the loans as financial assistance for Greece.
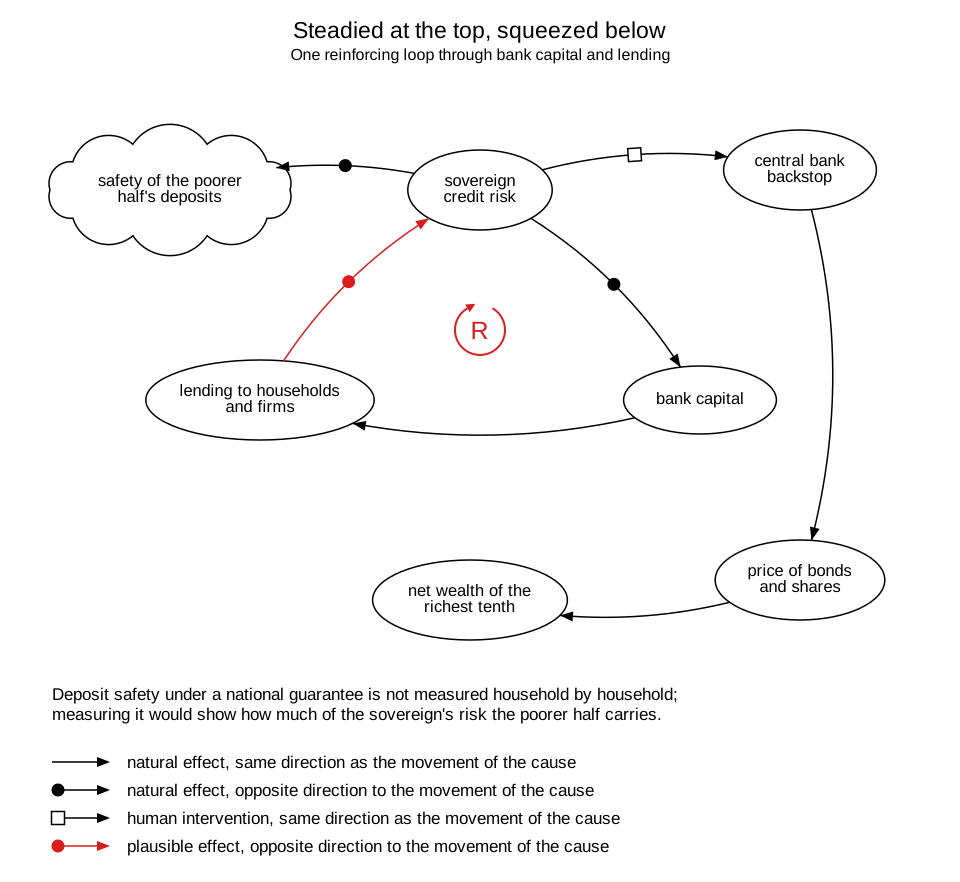
The squeeze on credit sorts people the same way. A bank protecting its capital ratio after sovereign losses can be forced to shed risk-weighted assets, for example by restricting lending to firms and households. Households with wealth do not need the loan. Households without it do.
In the euro area about 80% of equities, fund shares and bonds belong to the wealthiest tenth of households, while the poorer half keeps around a quarter of its small wealth in bank deposits. A central bank standing behind the bond market steadies the price of an asset held mostly at the top; lower borrowing costs for the state reach everyone else second-hand, through the spending those costs allow.
The deposits of the poorer half rest on a guarantee that is still national, and so dependent on “the credit standing of the home sovereign”. Where the state is strong, the guarantee is strong. Where the state is caught in the spiral, so are the savings.
The drift since the crisis runs partly against this. In Cyprus in 2013, where 47.5% of uninsured deposits at Bank of Cyprus were converted into equity while deposits under €100,000 were untouched, the loss stayed with those above the line.
But bail-in reaches only the direct route from a bank to the budget. The indirect routes, through lending, austerity and a deposit guarantee tied to its own state, still end at households, and they end hardest in the member states where the backstop is thinnest. The same euro does not carry the same protection everywhere it is held, nor the same bill.
After a crisis, a household that owns shares and bonds recovers through their prices. A household with little wealth meets the same recovery through its wage, its rent, the cost of borrowing and the price of the assets it does not yet own. Measured in euros, the distance between the two kept growing long after the crisis.
A house does two jobs in these balance sheets. For its owner it is an asset whose price can rise; for someone who does not own one, the same rise adds years of income to the cost of becoming an owner. A rise in household wealth can describe richer balance sheets without describing more equal ones.
The bottom line
Every turn of the spiral passes through one ratio, public debt to GDP. Weakened banks lend less; less lending means less investment and slower growth; slower growth raises the ratio at the centre of the spiral. The ratio divides one national total by another, and whose debt, whose income and whose loss sit inside either total does not appear in it.